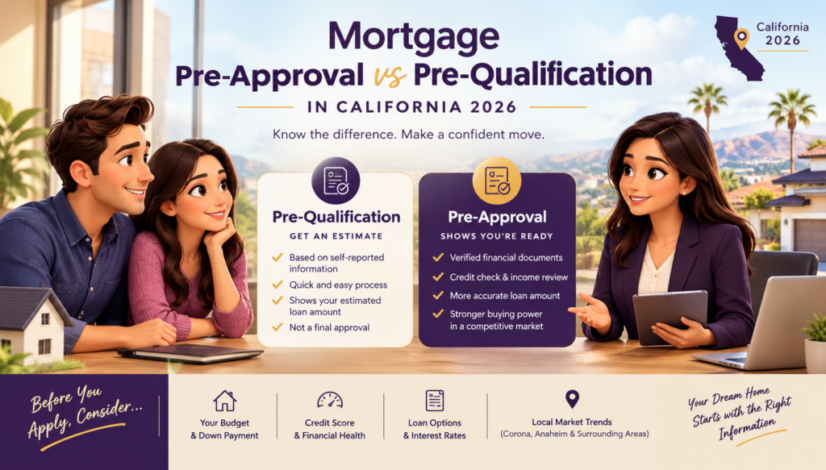
Mortgage Pre-Approval vs. Pre-Qualification in California: What Buyers Need to Know in 2026
Buying a home in California can become much easier when you understand your financing position before you start seriously shopping.
Two terms buyers frequently encounter are mortgage pre-qualification and mortgage pre-approval.
They sound similar, and lenders do not always use the terms in exactly the same way. The Consumer Financial Protection Bureau (CFPB) specifically notes that lenders can use “prequalification” and “preapproval” differently and may require different levels of documentation.
That means the important question is not simply:
“Do I have a preapproval?”
The better questions are:
- What information did the lender actually review?
- Was income verified?
- Were assets reviewed?
- Was credit checked?
- What assumptions were used?
- How long is the letter valid?
- What conditions could still affect the loan?
- Does the preapproval amount actually fit my personal budget?
For California buyers in areas such as Corona, Anaheim and surrounding Southern California communities, understanding these differences can help you prepare before making an offer.
What Is Mortgage Pre-Qualification?
A mortgage pre-qualification is generally an early assessment of how much you may potentially be able to borrow.
Depending on the lender, it may be based substantially on information you provide about your:
- Income
- Employment
- Debts
- Assets
- Credit profile
- Desired purchase price
- Down payment
However, the exact process varies.
The CFPB explains that lenders use the terms “prequalification” and “preapproval” differently. Some may issue a prequalification based primarily on information supplied by the borrower, while others may perform a more detailed review.
Therefore, the label alone does not tell you how strong the review was.
Why Buyers Still Use Pre-Qualification
Pre-qualification can be useful during the early planning stage.
For example, you may be trying to determine whether a California home purchase is realistic before you begin seriously viewing properties.
It can help you start thinking about:
- Potential purchase price
- Estimated loan amount
- Down payment
- Monthly payment
- Loan program options
- Documentation requirements
- Potential credit issues
It can also help identify questions that need to be addressed before a more detailed mortgage review.
What Is Mortgage Pre-Approval?
A mortgage pre-approval is a statement from a lender indicating that the lender is tentatively willing to lend up to a certain amount, subject to additional conditions and verification.
The CFPB explains that a preapproval letter is not a guaranteed loan offer. It is based on assumptions and can help demonstrate to a seller that the buyer is likely to obtain financing.
Freddie Mac similarly explains that a preapproval is not a guarantee because additional factors—including the property, income, assets, debts and loan type—are evaluated later in the process.
This distinction is extremely important.
Pre-Approval Does Not Mean Final Approval
A buyer can have a preapproval and still encounter additional underwriting requirements.
For example, after you have an accepted offer, the lender may need to evaluate:
- The specific property
- Appraisal or permitted valuation
- Title
- Homeowners insurance
- Property type
- Updated income
- Updated assets
- Employment
- Debt obligations
- Loan-program requirements
- Closing funds
- Other underwriting conditions
So a preapproval should be viewed as an important step toward financing—not the final loan decision.
Pre-Qualification vs. Pre-Approval: Key Differences
| Factor | Pre-Qualification | Pre-Approval |
|---|---|---|
| Purpose | Early financing estimate | More detailed buying preparation |
| Information | Often borrower-provided | Usually more detailed review |
| Credit | May or may not be checked | Often checked |
| Documentation | May be limited | Usually more extensive |
| Seller confidence | Can vary | Generally more useful for an offer |
| Loan amount | Estimated | Tentative borrowing amount |
| Final approval | No | No |
| Property review | Usually not completed | Usually not completed at this stage |
| Loan Estimate | Not necessarily | Not necessarily |
| Commitment to lender | No | No |
The exact process varies by lender.
This is why California buyers should ask how the lender defines and performs its preapproval process, rather than relying only on the title printed at the top of the letter.
Why Pre-Approval Matters Before House Hunting
The CFPB recommends getting preapproved before seriously shopping for a home and encourages consumers to contact multiple lenders.
A preapproval can help you understand your financing position before you make an offer.
It can help answer questions such as:
- What purchase price range should I consider?
- How much cash will I need?
- Which mortgage programs should I investigate?
- Are there documentation issues I need to solve?
- Are there credit issues that should be addressed?
- How much monthly payment am I personally comfortable with?
That last question is particularly important.
Your Preapproval Amount Is Not Your Personal Budget
Suppose a lender determines that you may qualify for a mortgage amount that supports a $900,000 purchase.
That does not mean you should automatically spend $900,000.
Your personal budget may need to account for:
- Property taxes
- Homeowners insurance
- HOA dues
- Mortgage insurance
- Utilities
- Maintenance
- Repairs
- Childcare
- Transportation
- Existing debt
- Emergency savings
- Future financial goals
The CFPB specifically emphasizes that the borrower—not the lender—must decide how much they are comfortable spending on a home.
A better question is:
“What monthly housing payment fits my overall financial plan?”
—not—
“What is the maximum amount the lender will approve?”
What Documents Are Typically Needed for Pre-Approval?
The exact documentation depends on the borrower and loan program.
A typical borrower may be asked for:
Income documentation
- Recent pay stubs
- W-2s
- Employment information
- Tax returns when required
- Other income documentation
Asset documentation
- Bank statements
- Retirement account statements
- Investment account statements
- Down-payment funds
- Closing-cost funds
- Reserve funds
Identification
- Government-issued identification
- Social Security information
- Residency documentation where applicable
Additional documentation
Depending on the borrower:
- Divorce or support documentation
- Gift-fund documentation
- Rental-property information
- Business records
- Profit-and-loss statements
- Business tax returns
- Lease agreements
- Other financial documentation
Self-employed borrowers may require a more detailed review because income can involve business structures, deductions, variable earnings and multiple sources of documentation.
What Happens During a Mortgage Pre-Approval?
A typical process may look like this:
Step 1: Initial Mortgage Consultation
The borrower discusses:
- Purchase goals
- Location
- Price range
- Down payment
- Income
- Credit
- Debts
- Employment
- Loan purpose
Step 2: Application
The lender collects the information needed to evaluate the borrower.
Step 3: Credit Review
The lender may obtain and evaluate the borrower’s credit information.
The CFPB notes that lenders may check credit as part of issuing a mortgage preapproval.
Step 4: Income and Asset Review
The lender evaluates the financial information and documentation required for the particular loan scenario.
Step 5: Loan Program Review
The buyer may compare potential options such as:
- Conventional
- FHA
- VA, if eligible
- USDA, if eligible
- Jumbo loan
- Other specialized mortgage programs
Step 6: Preapproval Letter
If the lender determines that the borrower meets its preliminary requirements, the lender may issue a preapproval letter specifying a tentative loan amount and relevant assumptions or conditions.
How Long Does a Mortgage Pre-Approval Last?
There is no single universal expiration period for every lender.
The CFPB notes that preapproval letters can have expiration dates and says they are typically valid for around 30 to 60 days, while Freddie Mac notes that borrowers can generally expect some preapproval letters to remain valid for 30 to 90 days, depending on the lender.
The important point is:
Check the expiration date on your actual letter.
If your home search continues for several months, the lender may need updated:
- Pay statements
- Bank statements
- Credit information
- Employment information
- Other financial documents
Does Pre-Approval Guarantee Mortgage Approval?
No.
This is one of the most important things California buyers should understand.
A preapproval is not the same as a final approval.
The final loan decision can depend on:
- Property appraisal
- Property condition
- Title
- Insurance
- Loan program requirements
- Updated income
- Updated assets
- Employment
- Credit
- Debt obligations
- Cash to close
- Underwriting conditions
A preapproval therefore provides useful information, but it does not eliminate the remaining mortgage process.
Can You Get Pre-Approved by More Than One Lender?
Yes.
In fact, the CFPB recommends contacting multiple lenders and comparing mortgage offers. It specifically recommends getting at least three preapprovals when shopping for a mortgage.
This does not mean you should collect dozens of preapproval letters.
Instead, consider comparing a manageable number of legitimate mortgage providers and asking each one:
- What loan programs do you offer?
- What information do you need for preapproval?
- How do you verify income?
- What assumptions are being made?
- How long is the letter valid?
- What are the estimated costs?
- When can I receive a Loan Estimate?
- What happens after my offer is accepted?
Does Getting Multiple Preapprovals Hurt Your Credit?
Mortgage credit inquiries can affect your credit, but the CFPB notes that when consumers obtain multiple preapprovals within a short period, there should generally not be a major impact on the credit score from those mortgage inquiries.
Credit-scoring treatment can depend on the scoring model and timing, so buyers should still discuss the process with their lender.
The important point is not to avoid comparison simply because you are concerned that every mortgage inquiry will necessarily be treated like a separate long-term credit-shopping event.
When Should California Buyers Get Pre-Approved?
For many buyers, preapproval makes the most sense when they are preparing to begin serious home shopping.
Getting it too early may mean that financial documents become outdated before you find a home.
Getting it too late can create problems if you find a property quickly.
A practical timeline is:
Planning stage → Mortgage consultation → Preapproval → Home search → Offer → Loan application/Loan Estimate → Underwriting → Closing
The CFPB recommends exploring mortgage choices before finding a home because once an offer is accepted, financing decisions can move quickly.
Pre-Approval for First-Time Homebuyers
First-time buyers often benefit from getting the mortgage review done early because they may have questions about:
- Down-payment requirements
- Closing costs
- FHA financing
- Conventional financing
- CalHFA programs
- MyHome Assistance
- Local assistance
- Mortgage insurance
- Gift funds
- Credit preparation
- Temporary buydown options
A preapproval can also reveal issues before the buyer becomes attached to a particular property.
For example, a buyer may discover that they need:
- Additional documentation
- A different loan structure
- More cash reserves
- Credit improvement
- A different price range
- Clarification of income
Finding that out before making an offer can be much more useful than discovering it during escrow.
Pre-Approval for Self-Employed California Buyers
Self-employed borrowers should start early because income documentation can be more complicated than a straightforward W-2 file.
Depending on the loan program, the lender may need to review:
- Personal tax returns
- Business tax returns
- Profit-and-loss statements
- Business bank statements
- Ownership percentage
- Business history
- Year-to-date income
- Debt obligations
The appropriate documentation depends on the loan program and borrower profile.
If you are self-employed in Corona, Anaheim or elsewhere in California, ask your mortgage professional before assuming your income will be calculated a certain way.
Pre-Approval and the 1-0 Buydown
For eligible purchase transactions, The Lending Mamba is covering the cost of your 1-0 Buydown.
A 1-0 Buydown can temporarily reduce the borrower’s scheduled payment during the first year, subject to the applicable loan structure and program requirements.
Important disclaimer: This offer is available on agency or government loans only. Eligibility, underwriting, property requirements, transaction structure and loan approval apply and may vary.
Buyers should understand the payment that applies after the temporary buydown period and should qualify based on the applicable permanent loan terms.
A temporary payment reduction should not be treated as a guarantee of savings or approval.
What Happens After Pre-Approval?
Once you find a property and the seller accepts your offer, the mortgage process becomes more specific.
The lender can now evaluate the actual:
- Property address
- Purchase price
- Loan amount
- Property type
- Occupancy
- Down payment
- Loan program
- Estimated taxes
- Insurance
- HOA costs
- Closing date
At this point, borrowers should compare official Loan Estimates, not simply rely on the preapproval letter.
The CFPB explains that after a buyer has a specific home, they should request, review and compare Loan Estimates from multiple lenders.
Preapproval vs. Loan Estimate
These are two different stages.
Preapproval
Helps answer:
“Can this lender tentatively work with my borrowing profile?”
Loan Estimate
Helps answer:
“What are the estimated terms and costs for this specific mortgage transaction?”
The CFPB states that borrowers can request Loan Estimates from multiple lenders and compare the offers.
That distinction is important because a preapproval letter by itself is not enough to compare the full economics of competing mortgage offers.
Common Pre-Approval Mistakes to Avoid
1. Choosing a lender solely because the preapproval amount is high
A larger approval amount does not automatically mean a better mortgage.
2. Assuming preapproval equals final approval
It does not.
3. Failing to disclose financial information
Incomplete information can create underwriting problems later.
4. Opening new credit
A new auto loan or credit card can change your financial profile.
5. Moving large amounts of money without documentation
Unexplained deposits or transfers can create additional questions.
6. Changing jobs without discussing it
Income and employment changes can affect qualification.
7. Assuming the lowest advertised rate is your actual rate
Your eventual pricing depends on the borrower, property, loan program, market conditions, points, credits and lock terms.
8. Shopping above your comfortable budget
A lender’s maximum approval is not necessarily your preferred budget.
How Corona and Anaheim Buyers Can Prepare
For buyers in Corona, consider preparing:
- Income documentation
- Bank statements
- Credit information
- Down-payment funds
- Closing-cost funds
- Property-tax estimates
- HOA information where applicable
- Insurance planning
For Anaheim buyers, the same preparation applies, with additional attention to:
- Local assistance eligibility
- HOA/project requirements
- Property taxes
- Insurance
- Potential city assistance programs
- Purchase price and income limits where applicable
Local programs and eligibility requirements can change, so buyers should verify current information before relying on a specific assistance program.
A Simple California Pre-Approval Checklist
Before you begin serious home shopping:
Financial preparation
☐ Review your credit
☐ Calculate your available down payment
☐ Identify closing-cost funds
☐ Review monthly debts
☐ Estimate a comfortable housing payment
Documentation
☐ ID
☐ Pay statements
☐ W-2s if applicable
☐ Tax returns if applicable
☐ Bank statements
☐ Investment/retirement statements
☐ Gift documentation if applicable
☐ Self-employment documents if applicable
Mortgage comparison
☐ Compare multiple lenders
☐ Ask what is actually verified
☐ Review loan-program choices
☐ Ask about estimated costs
☐ Understand preapproval expiration
☐ Ask what could still affect final approval
Home search
☐ Set your own purchase-price limit
☐ Tell your real estate agent your budget
☐ Understand taxes and insurance
☐ Check HOA costs where applicable
☐ Avoid major financial changes during the process
How The Lending Mamba Helps California Homebuyers
The Lending Mamba helps California buyers understand the mortgage process before they make an offer.
The review can include:
- Mortgage preapproval
- Loan-program comparison
- Down-payment planning
- Closing-cost planning
- First-time buyer programs
- FHA and conventional options
- Jumbo financing
- Self-employed mortgage options
- Investment-property financing
- 1-0 Buydown options for eligible transactions
For buyers in Anaheim, Corona and other eligible California markets, the goal is to create a clear picture of the financing before the buyer commits to a property.
Frequently Asked Questions
Q1. Is prequalification the same as preapproval?
A. No. The terms are used differently by lenders. Some prequalification processes rely heavily on borrower-provided information, while some preapproval processes involve more detailed verification. Ask the mortgage lender exactly what was reviewed.
Q2. Is a mortgage preapproval guaranteed?
A. No. A preapproval is not a guaranteed loan offer. Final approval depends on additional borrower, property and loan requirements.
Q3. How long does preapproval take?
A. The timeline depends on the lender, borrower and complexity of the file. Providing complete documentation promptly can help the lender complete its review efficiently.
Q4. How long does a preapproval letter last?
A. It varies by lender. CFPB says preapproval letters typically have expiration dates, often around 30–60 days; Freddie Mac notes that many may be valid for 30–90 days. Check your actual letter.
Q5. Should I get preapproved before looking at houses?
A. If you are preparing to shop seriously, getting preapproved can help you understand your financing position and demonstrate to sellers that you have taken steps toward obtaining financing.
Q6. Can I change lenders after getting preapproved?
A. Yes. A preapproval does not generally commit you to using that lender. The CFPB recommends comparing lenders and making the final lender decision after reviewing official loan offers.
Q7. Does preapproval tell me exactly what my monthly payment will be?
A. Not necessarily. The final payment depends on the specific property, loan amount, interest rate, taxes, insurance, mortgage insurance, HOA dues and other applicable costs.
Q8. Can self-employed buyers get preapproved?
A. Yes, but documentation and income analysis can be more involved depending on the loan program and business structure.
Final Thoughts
For California homebuyers, the difference between pre-qualification and pre-approval is less about the label and more about how thoroughly the lender has reviewed your financial information.
A useful preapproval should help you understand your potential borrowing range, likely loan options and documentation requirements—but it should never be treated as a guarantee of final approval.
Before making an offer:
- Review your finances.
- Compare multiple lenders.
- Understand your own budget.
- Prepare complete documentation.
- Get a meaningful preapproval.
- Compare official Loan Estimates once you have a property.
- Keep your finances stable through closing.
For California buyers in Corona, Anaheim and surrounding areas, starting the mortgage process early can help turn home shopping into a more organized financial decision.
The Lending Mamba
📞 657-777-0024 | 844-24-MAMBA
🌐 www.thelendingmamba.com